

Simple Checkbook Ledger

- 1.24K Reviews
- 3.4
- Downloads
- 100,000+
Our take on Simple Checkbook Ledger from Appgk
Keeping track of everyday spending does not always require a full banking platform. Sometimes I just want a private-feeling place to record what entered an account, what left it, and why the balance changed. That is the space where Simple Checkbook Ledger makes sense. It is a free finance app from Teelu Apps, built around the familiar checkbook idea rather than a large collection of investment, budgeting, or banking tools.
I approached it as a practical ledger, not as a replacement for a bank application. That distinction matters. The app’s store summary is “Manage your accounts with ease,” while its short description presents it as a simple checkbook ledger. In everyday use, that promise sets a useful expectation: the main value is orderly manual record-keeping. If you want a lightweight way to see where your money went, it has a clear purpose. If you expect automatic account connections, advanced financial planning, or a complete household money system, you should look more carefully before choosing it.
What Simple Checkbook Ledger feels like in everyday use
A focused approach to personal finance
What I like first is the narrow focus. Many finance apps try to do everything at once, combining bank synchronization, bills, subscriptions, credit scores, investments, goals, alerts, and charts. That can be useful, but it also creates more places to configure, authorize, and maintain. A checkbook ledger takes the opposite route: you enter transactions yourself and use the running record to understand the account.
That manual approach is especially useful for a checking account, a small cash reserve, or an account that is not supported by automatic connections. It can also work for someone who wants to separate a particular spending stream from a broader banking app. For example, I could use a ledger to follow money set aside for household repairs without mixing every purchase into my main financial dashboard.
Best Parts of Simple Checkbook Ledger
Things to Keep in Mind About Simple Checkbook Ledger
The trade-off is immediate. Manual entry gives me control over what appears in the record, but it also makes accuracy my responsibility. If I forget a purchase, mistype an amount, or delay recording a payment, the balance can become misleading. The app can organize the information I give it; it cannot replace the habit of entering transactions consistently.
Who gets the most value from it
I would recommend this app most readily to people who prefer a simple written-register mindset. It suits a student tracking a limited account, a household member managing a shared spending category, or anyone trying to understand routine outgoings without handing every transaction to an automatic finance service.
News and Features Related to Simple Checkbook Ledger

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
It is also a reasonable fit for users who want to practice deliberate spending. Entering a purchase by hand creates a small pause that automatic categorization removes. That pause can reveal patterns that are easy to ignore when transactions simply appear in a feed. A quick coffee, a transport payment, and a small online purchase may each feel insignificant, but recording them together makes their combined effect easier to notice.
I would be more cautious about recommending it to someone managing several complicated accounts, frequent transfers, business expenses, reimbursements, or investments. A manual ledger can become burdensome when the number of transactions grows. In that situation, a bank’s own transaction history or a more advanced budgeting service may save time, even if it requires more setup.
Don't want to read the full review?
Trust begins with a realistic expectation
The app has been available since Aug 3, 2016, and its current version is 3.5. It has passed the early-experiment stage in the sense that it is an established product rather than a newly released tool. Its average rating is 3.4, based on around 2.5 thousand ratings, and it has more than 100 thousand installs. I read those figures as signs of a real user base, but not as proof that every person will find the workflow smooth.
For me, the rating is a useful reminder to keep expectations measured. This is not an app I would choose because of a polished ecosystem or a large set of connected financial services. I would choose it because the ledger concept is understandable and because manual control can be preferable when I do not want to connect an account to another service.
Screenshots
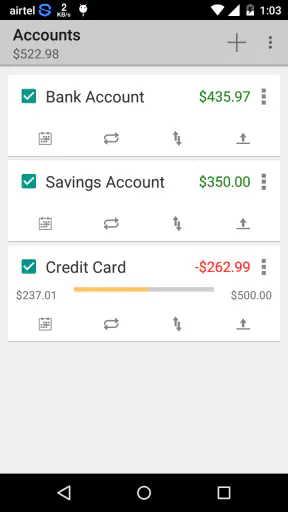
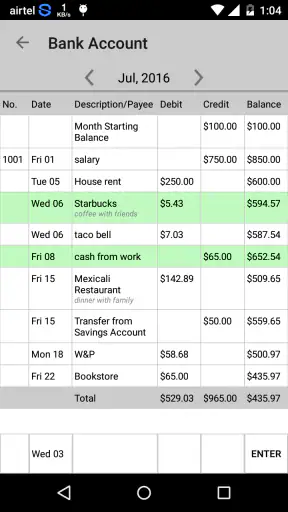
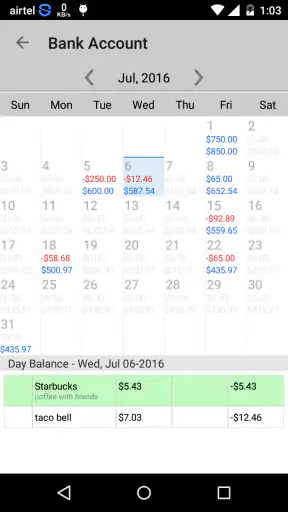
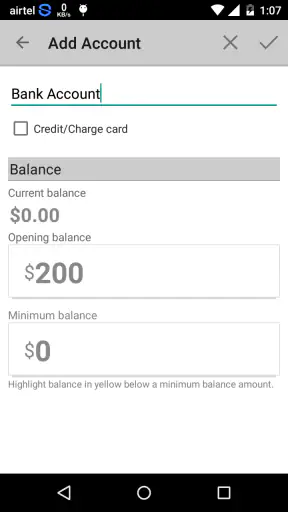
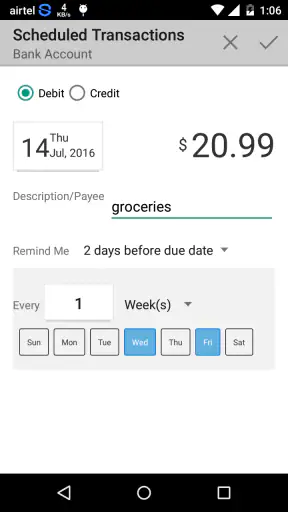
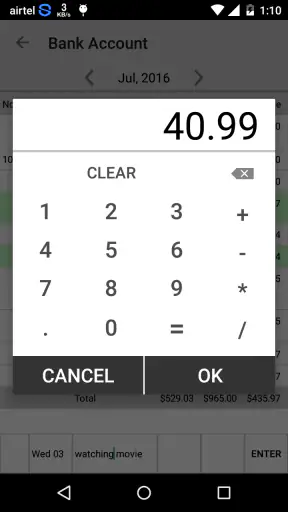
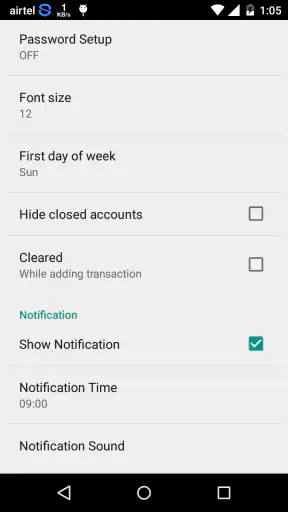
The developer is Teelu Apps, and the application is free to install. There are in-app purchases priced at $1.99 per item, so I would check the purchase screen carefully before confirming anything. The free starting point makes it easy to test the basic workflow, while the paid items mean I should not assume every possible option is included without cost.
Permissions, account access, and what I would check
Trust is particularly important in a finance app, even when it is only used as a manual ledger. The safest way to judge that trust is to look at the permissions requested during installation and at the choices shown inside the app. I would not grant a permission simply because the app belongs to the finance category. I would ask whether the requested access is clearly connected to recording and reviewing transactions.
I would also look for ordinary account controls: whether I can create or remove a ledger, edit an entry, correct a mistaken amount, and decide what information stays in the app. Those controls matter more to me than decorative charts. A finance tool should make it easy to fix an error without forcing me to rebuild an entire record.
Because the app is a manual checkbook rather than an automatic banking dashboard, I would avoid treating it as a secure vault for sensitive banking credentials. I would not enter online-banking passwords, card PINs, full security answers, or unnecessary identity information into a notes field. A ledger only needs enough detail to identify a transaction for my own use.
The app is rated for Everyone, which makes its presentation approachable for a broad audience. That age rating does not change my own privacy habits. I would still review the permission prompts, the purchase confirmations, and any account or backup choices before adding real financial details.
A practical routine that prevents misleading balances
The most useful workflow I found with this kind of app is not complicated, but it depends on consistency. I would enter a transaction as soon as possible, use a description that will still make sense later, and compare the running balance with the actual account regularly. “Store” is less helpful than “weekly groceries,” especially when I am trying to understand a month of spending.
A good routine is to reconcile the ledger after checking the bank statement. If the numbers differ, I would not simply change the balance until it looks right. I would search for a missing transaction, a duplicated entry, an incorrect date, or a payment that has not cleared. That habit turns the app from a basic list into a useful checking tool.
One non-obvious advantage of manual entry is that pending and completed payments can be handled deliberately. A card payment may appear in a bank account at a different time from when I made the purchase. If I record it too early or too late without a consistent method, the ledger can look wrong even when the final amount is correct. I would choose one rule—record at purchase time or at settlement time—and use it every day.
A realistic household example
Imagine I am responsible for a small household allowance account. At the start of the week, I record the opening balance. During the week, I add the supermarket purchase, a bus fare, and a repair item. On Friday, another family member asks how much remains. Instead of opening a full banking app and scanning unrelated transactions, I can inspect the focused ledger and explain the balance from the entries already recorded.
The method works well only if both people follow the same naming and timing rules. If one person records transfers as expenses and the other records them as income, the account history becomes confusing. I would therefore agree on a short convention before sharing the process: use clear descriptions, record transfers separately from purchases, and correct mistakes rather than adding an opposite transaction unless that reflects what actually happened.
This is also where the app may not be the best choice. If several people need simultaneous access, automatic updates, or a detailed audit trail, a shared spreadsheet or a purpose-built household budgeting service could be more suitable. The ledger approach is strongest when one person, or a small group with a clear routine, is responsible for keeping entries current.
Handling sensitive moments carefully
Financial records become more sensitive when descriptions reveal health costs, family circumstances, travel plans, or purchases that I would not want visible to someone holding my phone. I would use neutral but meaningful labels rather than writing unnecessary personal details. “Pharmacy” may be enough; a detailed medical explanation usually is not.
I would also think about screenshots, device sharing, and notifications. A balance or transaction description can expose more than expected if it appears on a shared screen. Before using the app for real records, I would check how entries are displayed, whether the phone itself is protected, and whether any optional sharing or export action is clearly under my control.
Another important moment is changing phones or reinstalling the app. A manual ledger is valuable only if the record survives the way I need it to. I would look for any visible backup, export, or transfer option before relying on it for long-term history. I would not assume that an app automatically preserves records across devices, and I would keep a separate copy of important information when the ledger matters for tax, reimbursement, or dispute purposes.
That caution is not a criticism unique to this application. It is a general rule for manually maintained financial records: the more important the history becomes, the less comfortable I am with having only one copy. I would periodically review how the app lets me retain or remove my entries and use only the options I understand.
Where it differs from banking apps and spreadsheets
A bank app has a major advantage: it normally shows transactions generated by the account itself. That reduces typing and makes it easier to confirm what actually cleared. Its weakness is that it may not offer the personal categories, notes, or separate tracking style I want. Simple Checkbook Ledger sits on the other side of that trade-off. It offers a deliberate record, but I have to maintain it.
A spreadsheet gives me greater flexibility. I can build formulas, add custom columns, create summaries, and share the file. However, that flexibility also creates more opportunities for broken formulas, inconsistent formatting, and accidental edits. A dedicated ledger can feel calmer because its purpose is narrower.
Budgeting apps with automatic connections are better for people who want a broad overview with minimal manual work. They can show spending patterns across accounts, but they may require more permissions, more account setup, and more trust in a connected service. I would select this app instead when the priority is keeping a small, controlled record rather than building a complete financial dashboard.
The important question is not whether one category is universally better. It is whether I value automation or direct control more. For a low-volume account, direct entry may be perfectly reasonable. For a busy financial life, automation may be worth the additional complexity.
Small habits that make the ledger more reliable
- Record transfers distinctly: moving money between accounts is not the same as spending it. Keeping that difference clear prevents an inflated picture of expenses.
- Use a reconciliation checkpoint: I would compare the ledger with the real account at a regular interval instead of waiting until I can no longer remember individual purchases.
- Keep descriptions searchable in spirit: even if I am not using advanced reports, consistent wording makes later review much faster.
- Separate temporary holds from final spending: when a payment is pending, I would follow one repeatable rule so the running balance does not swing unpredictably.
- Protect the record outside the app: for important history, I would use a clear retention method rather than assuming that reinstalling or changing devices will preserve everything.
These habits are more important than entering a large amount of detail. A short, consistent record is usually more useful than a richly described ledger that I update only occasionally.
Questions I would answer before installing
Is it free to try? Yes, the app is free, although in-app purchases are listed at $1.99 per item. I would explore the basic experience first and pay attention to what each optional purchase unlocks before deciding whether it adds meaningful value to my routine.
Will it replace my bank app? I would not use it that way. It is better understood as a manual account record. I would still rely on the bank or card provider for official balances, cleared transactions, security alerts, and account actions.
Is it suitable for sensitive financial information? It can be used for transaction records, but I would minimize personal details and avoid entering credentials or secrets. I would review permissions and visible privacy choices before adding real data, then protect the phone and retain important records responsibly.
Does it work for more than one account? The product is presented as a way to manage accounts, so I would consider it for separate ledgers, but I would test the exact account workflow before importing a large history. If I need complex transfers, shared access, or business accounting, I would compare it with a more specialized tool first.
What device support should I expect? The listed minimum operating-system requirement is 11. I would check that my Android or iOS device meets that requirement before planning to use it, especially if I am installing it on an older phone.
My cautious verdict
I see Simple Checkbook Ledger as a focused tool for people who want to write down transactions and stay close to their own financial records. Its strongest quality is not automation; it is the clarity that comes from a deliberately maintained ledger. That can be genuinely helpful for a small account, a spending allowance, cash tracking, or anyone who prefers not to connect financial accounts to another service.
At the same time, the manual model demands discipline. I would not recommend it to someone who wants effortless synchronization, sophisticated budgeting, investment tracking, or a complete view of several active accounts. The average rating of 3.4 suggests a mixed experience among users, so I would test the workflow with a few ordinary entries rather than committing immediately to a long financial history.
My recommendation is therefore conditional but positive: try it if your goal is a straightforward checkbook-style record and you are comfortable entering transactions yourself. Keep permissions, purchases, account details, and backup choices under your control. Used with that cautious mindset, this free finance app from Teelu Apps can be a practical companion for simple record-keeping. It is not a substitute for your bank, and it is not trying to be a complete financial command center—and knowing that boundary is the key to deciding whether it belongs on your phone.
Simple Checkbook Ledger FAQ
What is Simple Checkbook Ledger used for?
Simple Checkbook Ledger is designed to help you record and monitor personal finances without the complexity of a full banking app. You can typically enter income, expenses, deposits, withdrawals, and transfers, then review your running balance. It is useful for people who prefer manually tracking a checking account, cash account, or household budget in a straightforward ledger format.
Does Simple Checkbook Ledger connect directly to my bank account?
Simple Checkbook Ledger is primarily intended for manual transaction tracking rather than automatic bank synchronization. This means you generally enter transactions yourself instead of giving the app access to your banking credentials. That approach can improve privacy and give you more control, but it also requires consistency. If you want automatic imports, verify the current app description and supported features before downloading.
Can I use Simple Checkbook Ledger for multiple accounts or budgets?
The app may support organizing transactions across more than one account, depending on the version and platform you install. This can be helpful for separating checking, savings, cash, or other spending records. Before relying on it for detailed household finances, check whether your version includes account management, categories, recurring entries, and the reporting options you need, since available tools can vary.
Is Simple Checkbook Ledger suitable for tracking shared or business finances?
Simple Checkbook Ledger can be useful for basic shared or small-business record keeping when the main goal is maintaining a clear list of income and expenses. However, it should not automatically be treated as accounting software. It may lack features such as invoicing, tax reports, payroll, user permissions, or professional reconciliation. For business use, confirm its export and backup capabilities before storing important financial records.
Does Simple Checkbook Ledger offer backups, exports, or data protection?
Before entering a large amount of financial information, review how Simple Checkbook Ledger handles backups, exports, and device changes. A checkbook app is most valuable when your records can be restored after a lost phone, accidental deletion, or reinstall. Also examine its privacy policy and requested permissions. Avoid assuming that data is automatically synchronized or backed up unless the app explicitly confirms that feature.











